
Weekly Update- 22nd November 2026
Updated: 23 Nov 2026 • 2:33 am
Posted by:

NIFTY50
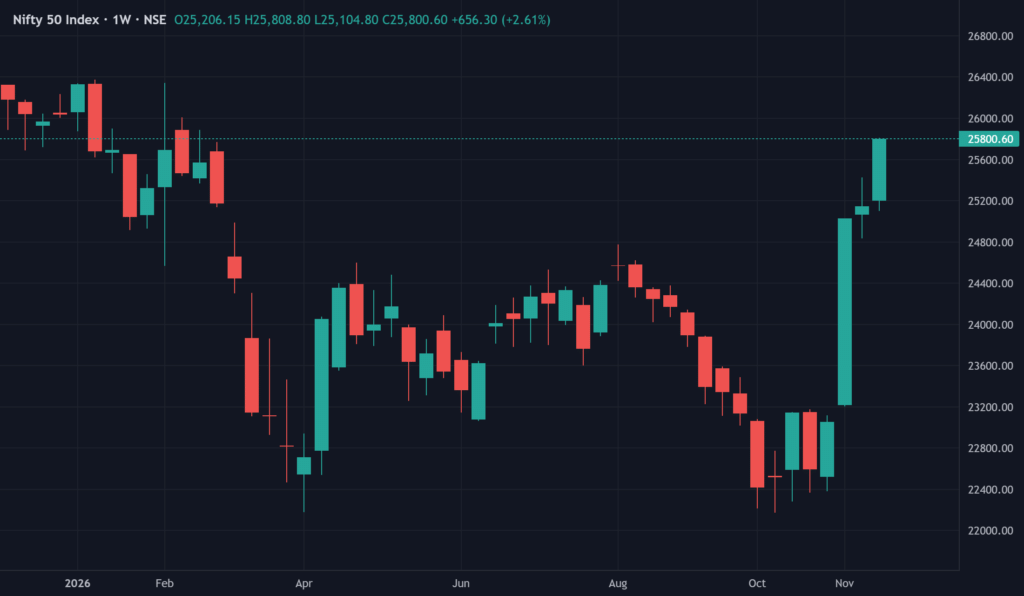
NIFTY50 at 25,801 gained 2.6% for the week and closed at the high of the week, snapping its consolidation of the previous week and extending the rally that began from the late-October low of 22,372. The index opened the week near 25,206, saw some profit booking on Wednesday, took support at the 25,105 level early on Thursday and staged a strong recovery to reclaim the 25,500 mark, before a broad-based rally on Friday took it to a high of 25,809 with buying across banks, FMCG, auto and financial stocks. The weekly candle is a strong bullish candle closing near its high, with a higher high and higher low compared to the previous week, which shows that buyers are firmly in control and the earlier resistance zone of 25,400–25,500 has now turned into support. The index is now just about 2% below the January high of 26,373. Immediate support is at 25,500, followed by 25,300 and 25,100. Resistance is at 25,900–26,000, followed by the January high of 26,373 and then 26,500. A sustained close above 26,000 would open the way toward 26,373 and beyond, whereas a fall below 25,300 would indicate profit booking toward 25,100–24,900. After a sharp move of about 15% from the lows in just four weeks, the index is overextended in the short term, so some consolidation near the 26,000 psychological level is possible. Overall, the trend is positive, with a buy-on-dips approach as long as the index sustains above 25,300, and 26,000–26,373 as the important zone to cross.
BANKNIFTY
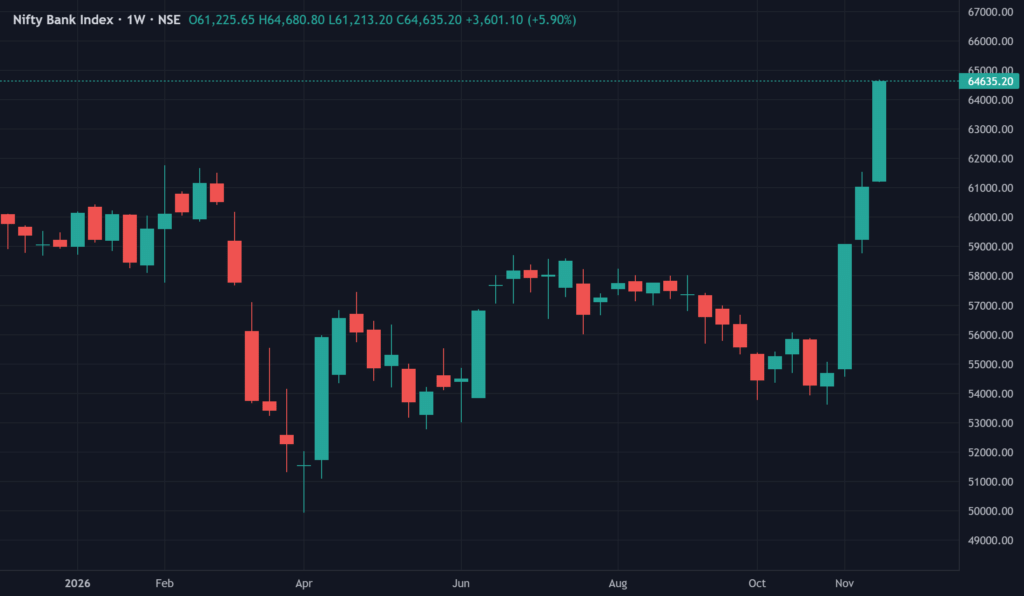
BANK NIFTY at 64,635 surged 5.9% for the week, which makes it the second consecutive weekly gain of more than 3%, and closed at the high of the week, clearly outperforming NIFTY50. The index opened the week near 61,226, crossed the February high of 61,765 on Tuesday, and kept climbing through the week with a strong uptrend, closing above 63,000 on Thursday and then a big 2.5% jump on Friday to touch a fresh high of 64,681, led by PSU banks (+6.7%) and private banks (+5.7%). The weekly chart shows a very strong bullish candle with a higher high and higher low, and the old resistance zone of 61,500–62,000 has now turned into a strong support. After such a sharp move the index is overbought in the short term, and some profit booking can come near the psychological 65,000 mark. Immediate support is at 63,000, followed by 62,300 and 62,000. Resistance is at 65,000, followed by 66,000. The outlook remains positive and the outperformance is likely to continue as long as the index sustains above 62,000 on a closing basis, and a close above 65,000 would open the way toward 66,000. A close below 62,000 would indicate a deeper correction toward 61,500. Overall, BANK NIFTY remains in a strong uptrend, with 62,000–63,000 as the key support zone and 65,000 as the next hurdle to cross.
TOP GAINING SECTOR
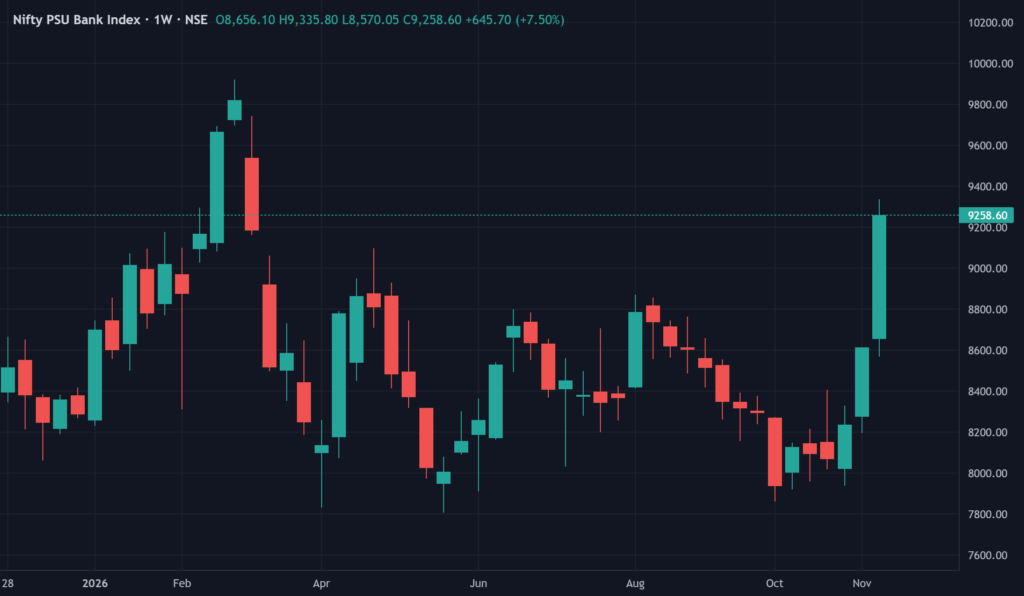
NIFTY PSU BANK was top gainer sector for the week, up about 6.7%
Major gainers were:-
PUNJAB NATIONAL BANK:- up by 8.77%
BANK OF MAHARASHTRA:- up by 8.45%
STATE BANK OF INDIA:- up by 7.88%
UNION BANK OF INDIA:- up by 7.81%
BANK OF INDIA:- up by 6.88%
TOP LOSING SECTOR
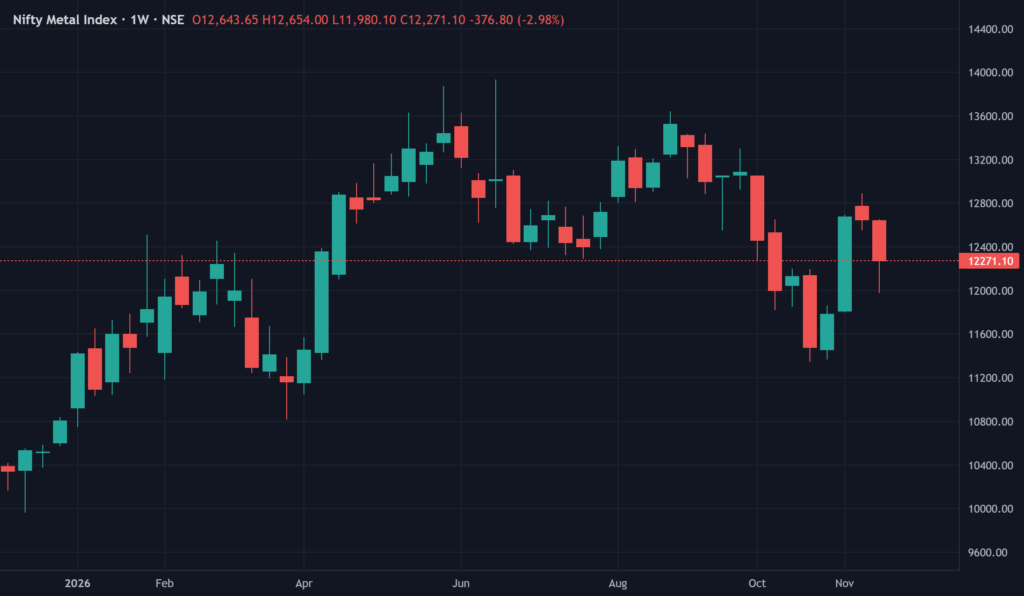
NIFTY METAL was top losing sector for the week, down about 3.0%
Major losers were:-
VEDANTA:- down by 8.33%
NATIONAL ALUMINIUM:- down by 8.12%
SAIL:- down by 6.86%
HINDUSTAN ZINC:- down by 5.99%
APL APOLLO TUBES:- down by 5.77%
IMPORTANT NEWS
- The NIFTY50 rose 2.6% to 25,800.60 and BANK NIFTY surged 5.9% to 64,635, a fresh high for the year and well above its February peak. The rally was broad-based, with PSU Banks (+6.7%), Private Banks (+5.7%), FMCG (+3.6%) and Auto (+3.1%) leading the gains, while Metal (-3.0%) and IT (-1.9%) lagged.
- Budget expectations built up as Finance Minister Nirmala Sitharaman held the fifth pre-Budget consultation for the FY28 Union Budget with the capital markets, banking and insurance sectors, where stakeholders sought cuts in LTCG tax and STT. The Defence Secretary proposed a 20% increase in defence capital expenditure, and the government set a disinvestment target of ₹80,000 crore for FY27, with the Mahanadi Coalfields IPO planned at ₹8,518–8,981 crore.
- Global cues were supportive, with China describing the meeting between President Xi Jinping and US President Trump as positive and constructive, and the Quad meeting taking place with the leaders of the US, India, Japan and Australia. India's Commerce Secretary said the India-US trade deal will take time but is expected to be concluded soon, while the US introduced new rules restricting remote access to advanced AI chips.
- India's October WPI inflation rose to 12.29% from 11.39% in September, slightly below the estimate of 12.40%. Copper fell as much as 4.2% on the LME, its biggest decline since March, which weighed on metal stocks, with Vedanta, NALCO and SAIL among the biggest losers of the week.
- On the corporate front, BSE's CO BANKEX became the first Indian sectoral index futures contract approved by the US CFTC, Urban Company raised about ₹2,500 crore through a QIP, and ITC plans staggered cigarette price hikes in 2027. Alkem Laboratories received a USFDA warning letter for its Daman facility, which contributes about 9.2% of its total revenue.
Recent Articles
Reliance Industries Share Price Prediction for Monday (23 Nov 2026): Stock Ends Almost Flat as Banks Lead
20 November 2026
Infosys Share Price Prediction for Monday (23 Nov 2026): Stock Edges Up 0.56% After a Spike to 1,118.80
20 November 2026
TCS Share Price Prediction for Monday (23 Nov 2026): Stock Rebounds 1.43% After Two Falls
20 November 2026
ICICI Bank Share Price Prediction for Monday (23 Nov 2026): Stock Gains 1.93% on Heavy Volume
20 November 2026
Note: This blog is for information purpose only. Investments and trading are subject to market risks, read all scheme related documents carefully.
Reviews






Recent Posts
Reliance Industries Share Price Prediction for Monday (23 Nov 2026): Stock Ends Almost Flat as Banks Lead
Infosys Share Price Prediction for Monday (23 Nov 2026): Stock Edges Up 0.56% After a Spike to 1,118.80
TCS Share Price Prediction for Monday (23 Nov 2026): Stock Rebounds 1.43% After Two Falls
ICICI Bank Share Price Prediction for Monday (23 Nov 2026): Stock Gains 1.93% on Heavy Volume
Bharti Airtel Share Price Prediction for Monday (23 Nov 2026): Stock Edges Up 0.83% and Closes Near Its High

Uniresearch Global Pvt Ltd
Research Analyst
SEBI Registration Number — INH000013776
Uniresearch is a subsidiary of Univest Communication Technologies Private Limited
Company Address: Registered Address: Ground Floor, Unitech Commercial Tower 2, Block B, Greenwood City, Unit 1-3, Sector 45, Gurugram, Haryana 122003
Write to us : support@univest.in, compliance@univest.in
Verify on SEBI registry →RESEARCH ANALYST
Get SEBI Registered
advice on the stocks
trending today.
Get 3 FREE Trade Ideas

for Startups Accelerator 2024

Trusted by 1Cr Indians

Awarded No.1 by Economic Times